

















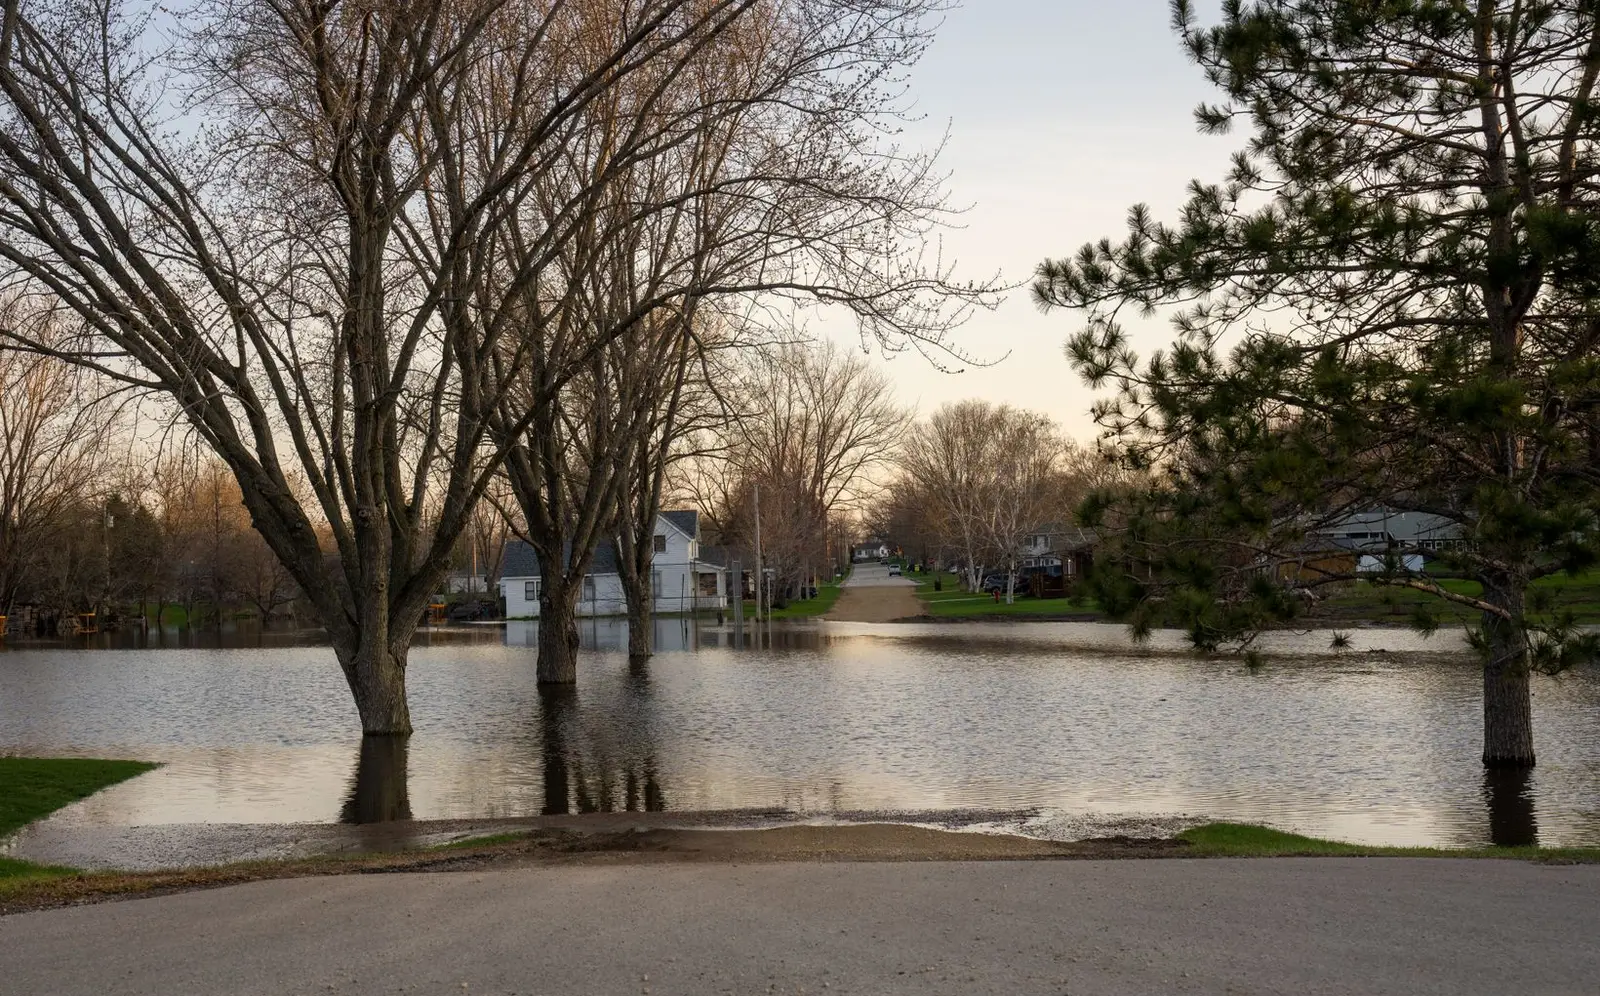
If you own a house, look up your flood zone this week. FEMA moved the lines over the summer, and in more than 100 communities across 12 states, addresses that were outside the high-risk zone are now inside it.
Nobody is required to call you. The clock runs anyway, and it’s 45 days long.
Cotality, the property data firm, counted the newly mapped addresses on September 17. Escambia County, Florida picked up 2,344 properties. Pender County, North Carolina got 678. Chattanooga, 635. Ithaca, New York and Methuen, Massachusetts tied at 428 apiece. That’s the top five of a list running past a hundred communities.
Then Cotality says the quiet part: “change notifications aren’t mandatory, and some homeowners are left out of the loop.”
The deadline is not optional, though. Federal law, 42 U.S.C. 4012a(e), says that once your lender determines your building sits in a Special Flood Hazard Area without coverage, it tells you to buy flood insurance at your own expense. “If the borrower fails to purchase such flood insurance within 45 days after notification,” the lender “shall purchase the insurance on behalf of the borrower and may charge the borrower for the cost of premiums and fees.”
That’s force-placed insurance. Here is how the OCC’s own consumer site describes it: “often more expensive than coverage under a policy purchased directly by the borrower.” Your servicer is not shopping for you. It’s buying a policy and sending you the bill.
The bill lands in escrow, which is where a fixed mortgage payment quietly stops being fixed. Cotality puts escrow payments up 45 percent against five years ago. In the states where the maps got rewritten hardest, escrow “costs now represent over one-third of a mortgage payment”: North Carolina up 30 percent, Missouri 36 percent, New York 41 percent. For one homeowner in ten, the escrow line is already bigger than principal and interest combined.
Your rate is locked. This isn’t.
It lands hardest on FHA borrowers, which Cotality names outright: lower down payments, tighter debt-to-income, “a thinner financial cushion to absorb sudden cost increases.” A few hundred dollars of new escrow a year is a rounding error on one budget and a missed payment on another.
Do this. Search your own address, not your neighborhood, on FEMA’s Flood Map Service Center. If you’re newly inside the zone, call an agent this week and get a flood quote in your own name. Beating your servicer to it is the whole game.
If a policy has already been force-placed on you, you are not stuck with it. Buy your own and send proof. The same statute gives the lender 30 days from getting confirmation of your coverage to cancel what it bought and refund every premium and related fee you paid for the overlap.
Then read the escrow line on your next statement instead of the total, because a servicer can re-run an escrow analysis and raise your monthly payment without your rate moving a basis point. That’s the trap we walked through earlier this month. Our mortgage calculator will show you what a new insurance line does to the monthly number before your servicer does.
One date for the calendar. The federal flood program’s authorization now runs to midnight on December 11, a deadline that already moved once this fall. If you need a brand new policy, don’t schedule it for the week of a congressional funding fight. Buy it now, while the counter is open. More on what moves your payment in the mortgages hub.
How Candid Yak makes money. Some of the products we write about pay us if you apply or sign up through our links. That never changes our verdict, our rankings, or the numbers in this article. We call a bad deal a bad deal whether it pays us or not. Some brands shown in our comparison tools are placeholder examples while we finalize partner agreements, and we label them as such.
Sources
- FEMA changes flood markets with a new calculation (Cotality, September 17, 2026)
- FEMA's New Flood Maps Means More Homes Require Flood Insurance: Cotality (Insurance Journal, September 21, 2026)
- 42 U.S. Code 4012a, Flood insurance purchase and compliance requirements and escrow accounts (Legal Information Institute, Cornell Law School)
- How much does flood insurance cost? (HelpWithMyBank.gov, Office of the Comptroller of the Currency)