

















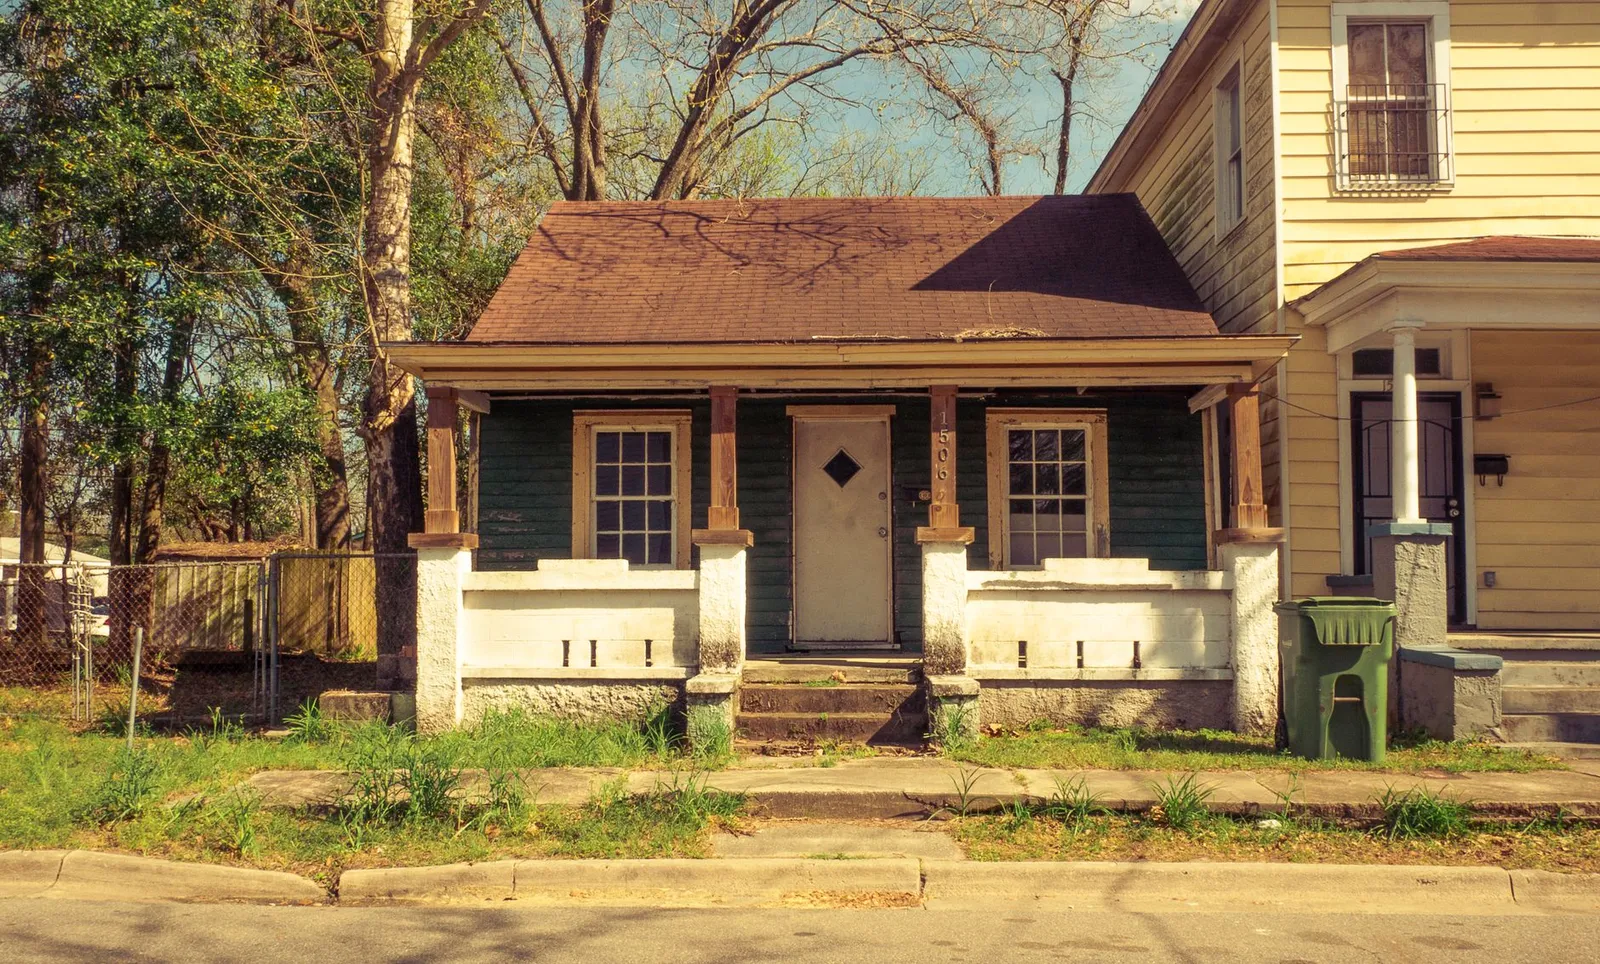
If an FHA deal of yours ever died over peeling paint on a detached garage, a missing oven, or an attic the appraiser could not get into, FHA just proposed deleting the rule that killed it.
The draft went up September 22. Feedback closes November 6. And none of it touches the loan you are closing next month.
FHA posted the rewrite to its Single Family Drafting Table after a Request for Information it issued in May. The agency’s own framing is the tell: these Minimum Property Requirements have not been substantially revised in more than two decades.
Here is what comes off the list, straight from the draft’s summary tables.
Kitchen appliances, gone. FHA’s stated reason is that the requirements “were an unnecessary burden and did not impact criteria that all homes be safe, sound and secure.” Defective exterior paint surfaces, gone as an “unnecessary repair requirement.” Roof covering, gone. Attic observation and crawl space observation, both gone, meaning the appraiser no longer has to crawl under your house or climb into the attic. Heating and cooling, gone. Lead-based paint stays, but the required repair narrows from the entire property to the dwelling structure, so your shed and your fence stop counting.
That is a real list. Now read the catch.
The checklist becomes one letter grade
Everything above gets replaced by a single holistic judgment. FHA proposes adopting the condition ratings appraisers already use for Fannie and Freddie, C1 through C6, and setting a minimum of C4 for a property to be acceptable at all. Quality ratings run Q1 through Q6, minimum Q5.
C4 is the ordinary older house. The draft defines it as a dwelling that “has been adequately maintained and exhibits moderate wear and tear,” carrying deferred maintenance that is “generally minor or cosmetic in nature.” Dated kitchen, worn carpet, tired trim. Fine.
C5 is where your file dies. And FHA’s own example of a C5 property is this: “Roofing that is significantly worn, cupped or curled but with no apparent active leaks.”
Then the draft says what happens. A property with C5 or C6 deficiencies “is not acceptable collateral unless all issues that caused the property to be rated with a C5 or C6 condition rating are cured before Closing Date.”
So the roof rule did not disappear. It moved. A worn roof with no leak used to be one handbook item you could argue about. Under the draft it is a letter grade that fails the entire file.
What to actually do
Closing this fall? Ignore all of it. Today’s handbook governs your appraisal, and anyone telling you the paint stopped mattering is guessing at a draft.
Selling an older home to an FHA buyer? Do not gut a dated but working kitchen chasing this. Under the draft, dated is C4. Missing is C5. Those are opposite outcomes.
Have an opinion? Say it by November 6. FHA says this round already reflects what came back from the May request, so the comments go somewhere.
Then price the loan like an adult. Our mortgage picks and the mortgage calculator show what each quote does to the payment, and the mortgages hub covers the rest of the FHA rules worth knowing, including the well distance requirement FHA already waived this summer.
Twenty years of appraisal fights over stoves and shed paint, and the fix is a letter grade. Better. Just not softer than it sounds.
How Candid Yak makes money. Some of the products we write about pay us if you apply or sign up through our links. That never changes our verdict, our rankings, or the numbers in this article. We call a bad deal a bad deal whether it pays us or not. Some brands shown in our comparison tools are placeholder examples while we finalize partner agreements, and we label them as such.