

















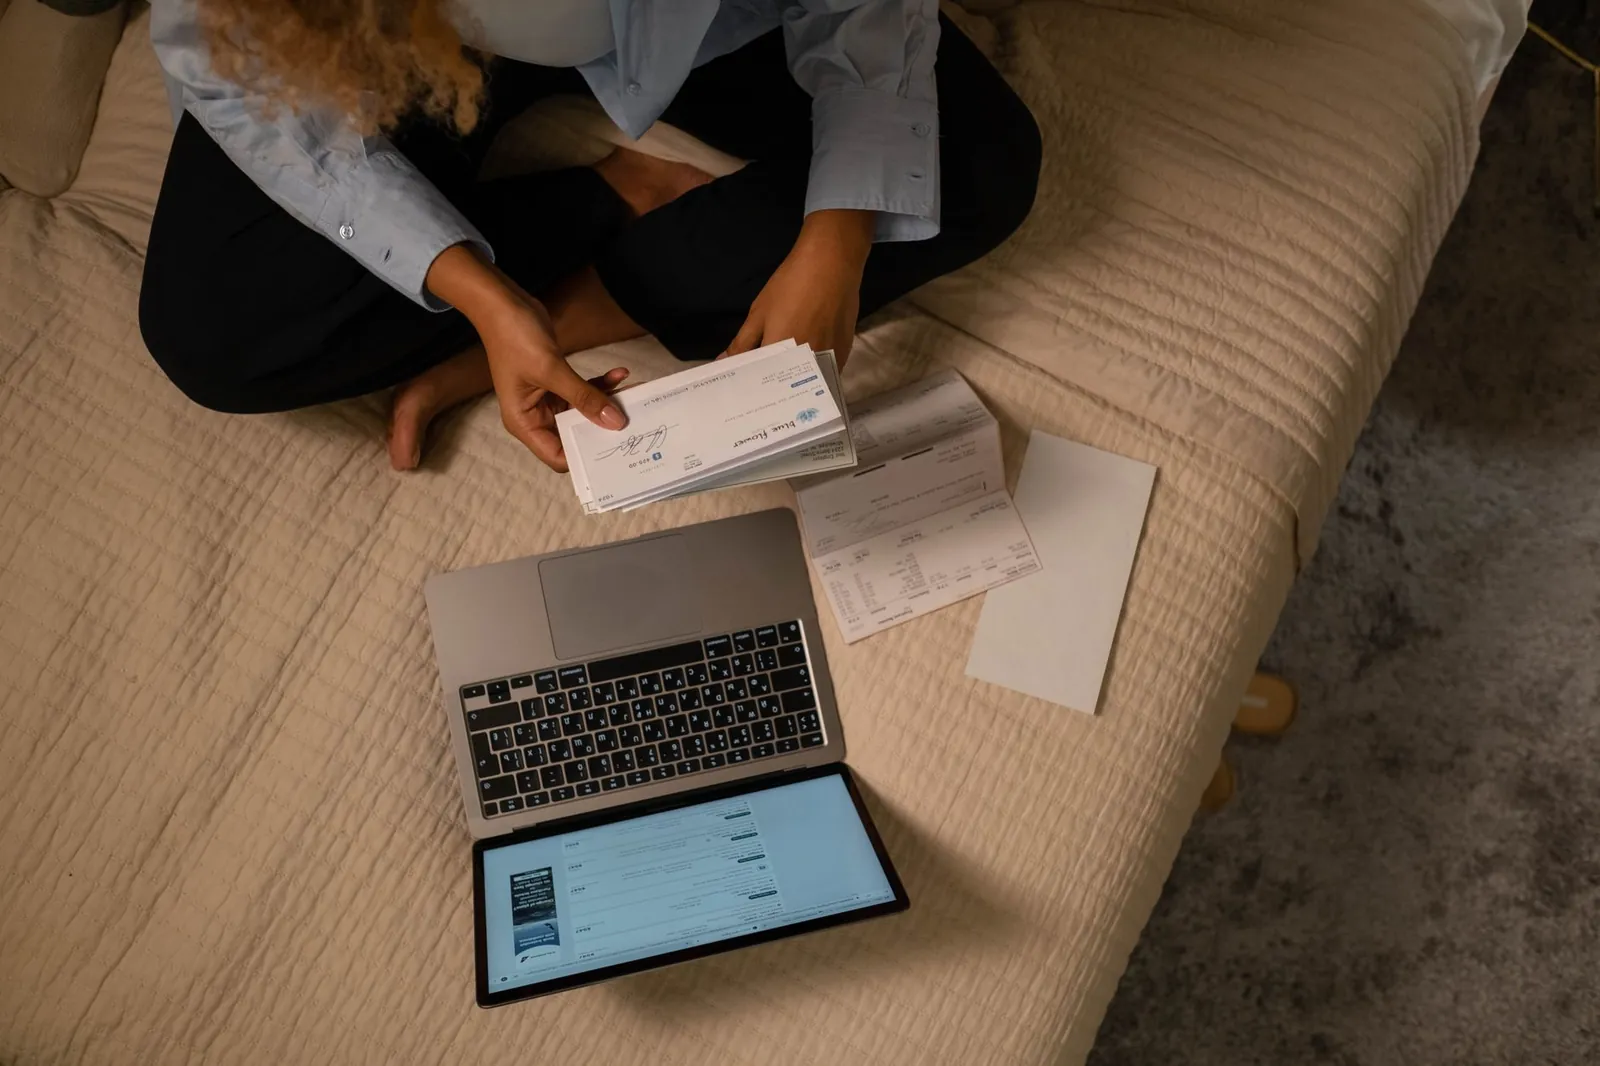
Update, October 10, 2026: Both sides of this trade moved since June, and the gap held. Bankrate's average personal loan rate is now 12.54% (as of October 7), up from near 12%. On the card side, the Fed's October 7 G.19 release puts the average rate on card accounts that actually pay interest at 22.36% in August. Then the Fed hiked on September 16 and prime went to 7.00%, which pushes variable card rates up again on balances you already owe. A personal loan's rate is fixed the day you sign. The math below now uses 22.36% and 12.54%, and the savings still come to about $1,800. One thing we've added: price the origination fee before you sign, because a big fee can eat most of that.
If you are carrying a credit card balance at 22%, there is a decent chance you can refinance that exact debt down to about 12%. Same money owed, far less interest, one fixed payoff date. The math is not complicated. The discipline it requires is.
Start with the gap. Bankrate's benchmark puts the average personal loan at 12.54% for a borrower with a 700 credit score. Credit card balances, by contrast, commonly run 18% to 30%, per the Federal Reserve Bank of Richmond, and the Fed's own data puts the average on card accounts paying interest at 22.36%. Credit unions average 10.64% on personal loans, per Bankrate, and federal credit unions can't charge more than 18%. A personal loan is a fixed lump sum you repay in equal monthly payments over a set term, usually two to five years. Unlike a card, the rate does not float and the balance actually goes down on a schedule instead of resetting every time you swipe.
The average personal loan runs about 12.5%. Cards that charge interest average 22.36%. That spread of nearly 10 points is the whole opportunity.
Run it on a real number. Say you owe $10,000 and commit to clearing it in three years. Left on a card at 22.36%, that costs about $384 a month and roughly $3,816 in interest. Move it to a 12.54% personal loan and it drops to about $335 a month and roughly $2,050 in interest. Same three years, same debt gone at the end, about $1,800 less handed to a lender. Get the credit union average of 10.64% instead and the gap is closer to $2,100. That is real money, and it is the cleanest case for consolidation.
Here's the trap, and it is the reason most consolidations fail. You move the $10,000 off your cards, your cards now read $0, and they feel like found money. Three months later there is a new balance on the card and the loan payment on top of it. Now you owe more than when you started, at two rates. The personal loan only wins if the cards stay at zero. That is not a math problem. It is a behavior problem, and the lender is betting you have it.
So here is the move, in order. First, check your rate. Most lenders show your personalized rate with a soft credit check that does not ding your score, so you can see your real number before committing. If it is not meaningfully below your card rate, a balance is not worth refinancing, and you are better off attacking the card directly. Then compare APRs, not rates. Many online lenders take an origination fee out of the loan up front, and a 5% fee on $10,000 is $500 of your $1,800 gone before you start. Compare offers on our best loan rates page and run your balance and term through the debt-payoff calculator so you see the payoff date in writing.
Ranking
Our top-rated debt consolidation loans
Lenders that make rolling high-interest debt into one payment cheapest.
| Rank | Company | Best for | Key stat | Score | Apply |
|---|---|---|---|---|---|
| 1 | SoFiPersonal Loan | Best for large loans | 6.49% - 35.49% APR fixed with autopay + member discounts (September 2026) | 9/10 | |
| 2 |  UpgradePersonal Loan | Best for debt consolidation | 7.74% - 35.99% APR, 1.85% - 9.99% origination fee (September 2026) | 8.9/10 | |
| 3 |  LightStreamPersonal Loan | Best for low rates | 9.99% - 24.94% APR with autopay, no fees (October 2026) | 8.8/10 | |
| 4 |  DiscoverPersonal Loan | Best for no-fee consolidation | 6.99% - 24.99% APR, no fees (September 2026) | 8.7/10 | |
| 5 | Best EggPersonal Loan | Best for fast funding | 6.99% - 35.99% APR, 0.99% - 9.99% origination fee (September 2026) | 8.6/10 |
Second, if you pull the trigger, treat the cards as paid off, not available. Some people cut the limit, freeze the card, or delete it from their phone's wallet. Whatever it takes to keep that $0 at $0 until the loan is gone.
Done right, this is one of the few moves that costs nothing and saves four figures. Done halfway, it doubles your problem. Your call, but only one version of it is smart.
How Candid Yak makes money. Some of the products we write about pay us if you apply or sign up through our links. That never changes our verdict, our rankings, or the numbers in this article. We call a bad deal a bad deal whether it pays us or not. Some brands shown in our comparison tools are placeholder examples while we finalize partner agreements, and we label them as such.
Sources
- What is the average personal loan rate for October 2026? (Bankrate, Bankrate Monitor data as of October 7, 2026)
- G.19 Consumer Credit, Terms of Credit, released October 7, 2026 (Board of Governors of the Federal Reserve System)
- H.15 Selected Interest Rates, bank prime loan rate 7.00% (Board of Governors of the Federal Reserve System)
- Buy Now, Pay Later: Recent Developments and Implications (Federal Reserve Bank of Richmond)