

















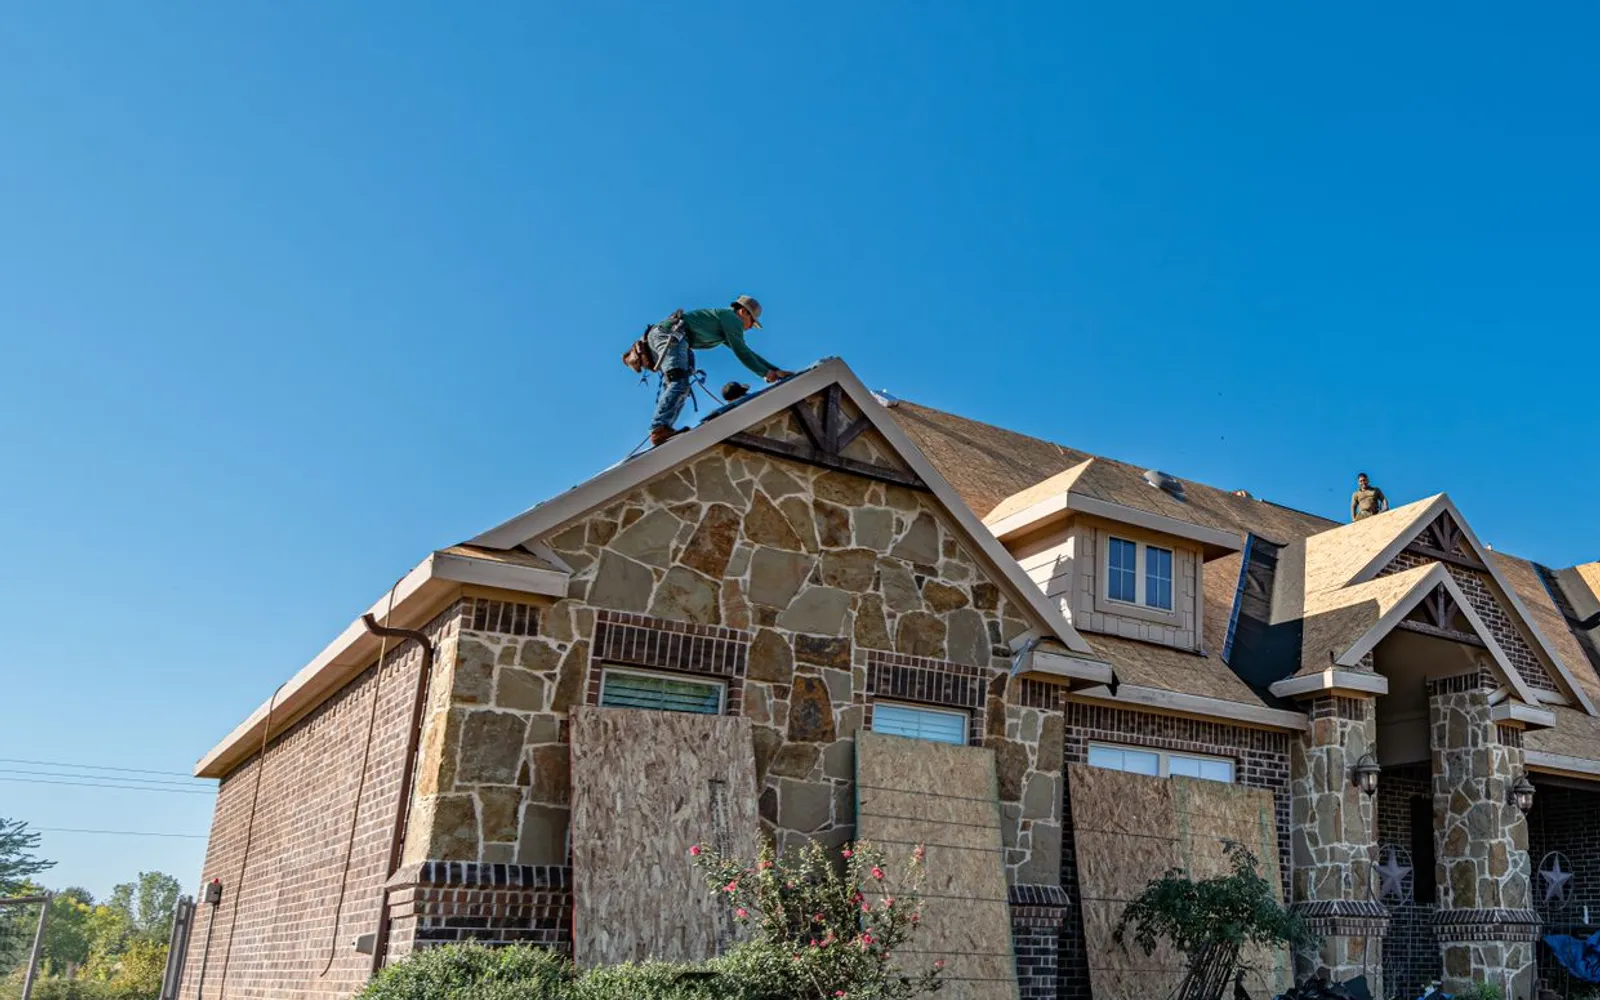
If you paid extra for an impact-resistant roof in Texas, whether that ever shows up on your bill is your insurance company’s call. Not the state’s. Yours is only to ask.
On September 16 the Texas Department of Insurance sent every company writing residential property in the state a bulletin about exactly that. Commissioner’s Bulletin B-0008-26 says TDI “encourages all property and casualty insurance companies operating in Texas to develop meaningful, actuarially supported premium discounts” for loss mitigation. It names three things: homes built or retrofitted to the IBHS FORTIFIED Home standard, impact-resistant roofing materials, and work done ahead of a wildfire.
The reasoning is hard to argue with. “Texas law requires rates to be based on risk,” the bulletin says. “When a homeowner spends money today to prevent tomorrow’s claim, insurers should recognize that investment with meaningful premium savings.”
Correct. Now read the verb again.
Encourages. The bulletin points to Insurance Code Chapter 2251, which permits companies to group risks by classification when they price a policy. A company that wants to add or widen a mitigation credit files it through SERFF like any other rate change. A company that would rather not, doesn’t.
The state certifies the roof. Your insurer prices it.
TDI is blunt about where that leaves you. Its home insurance guide says “each company decides what discounts to offer and the amount of the discount.” Its own page on impact-resistant roofing credits says the amount for each class of material “is established by the insurance company on a company-by-company basis.”
Alabama does not run it that way. Alabama Code 27-31D-2 says insurers “shall provide a premium discount or insurance rate reduction” on wind coverage for homes retrofitted to the FORTIFIED standards. Shall. It has read that way since May 14, 2009.
Why the roof is the fight worth having
Texas homeowners paid an average of $3,489 last year, TDI’s preliminary 2025 figure, against $1,987 in 2020. The Dallas Fed put the 2019 to 2024 run-up at 60% in Texas versus 30% nationally.
Hail is the reason. Of the insured homeowners losses TDI counts for 2025, hail runs $2.32 billion. Wind is $757 million, water and freeze $722 million, fire $614 million. Hail by itself beats those three added together.
A Class 4 roof is the one purchase a homeowner can make that aims straight at the biggest number on that list. Buying it and getting nothing back is a bad trade, and the state has now formally noticed.
Do this before you pick a shingle
Call your insurer and ask for the written list of mitigation credits it files in Texas and the amount of each one. Not “do you have a roof discount.” The list, and the numbers. Then ask a second carrier the same question, because the credit is set company by company and comparing is the part of this you control.
If the roof is already on, have your contractor complete TDI form PC068, the impact-resistant roofing installation form, and get it to your agent with the UL 2218 class on it. Class 4 earns the highest credit. Ask for written confirmation that it applies to the current term, not just the next renewal.
One more line to keep. The bulletin tells companies to stop “forcing homeowners to submit separate, redundant loss mitigation surveys or inspection forms.” If a third form shows up, quote it back.
If your roof is fine, file this away. Pull it out the week hail takes it, alongside the cheaper roof payout your policy may have quietly switched to.
How Candid Yak makes money. Some of the products we write about pay us if you apply or sign up through our links. That never changes our verdict, our rankings, or the numbers in this article. We call a bad deal a bad deal whether it pays us or not. Some brands shown in our comparison tools are placeholder examples while we finalize partner agreements, and we label them as such.
Sources
- Commissioner's Bulletin B-0008-26, Premium discounts for loss mitigation, September 16, 2026 (Texas Department of Insurance)
- Texas homeowners insurance market overview (Texas Department of Insurance)
- Products qualifying for impact-resistant roofing credits (Texas Department of Insurance)
- Home insurance guide, CB025 (Texas Department of Insurance)
- Insurance and your roof: What to know when buying a policy or filing a claim (Texas Department of Insurance)
- Alabama Code 27-31D-2, Premium discount or insurance rate reduction, Fortified existing homes
- Texas homeowners pay high insurance costs, face rising premiums (Federal Reserve Bank of Dallas, Southwest Economy, Mariam Yousuf, April 15, 2026)